Describe the equipment accurately
List the pickup or medium-duty truck, trailers, equipment values, VINs and any permanently attached accessories. Goose-neck and flatbed trailer exposures should be included when relevant.
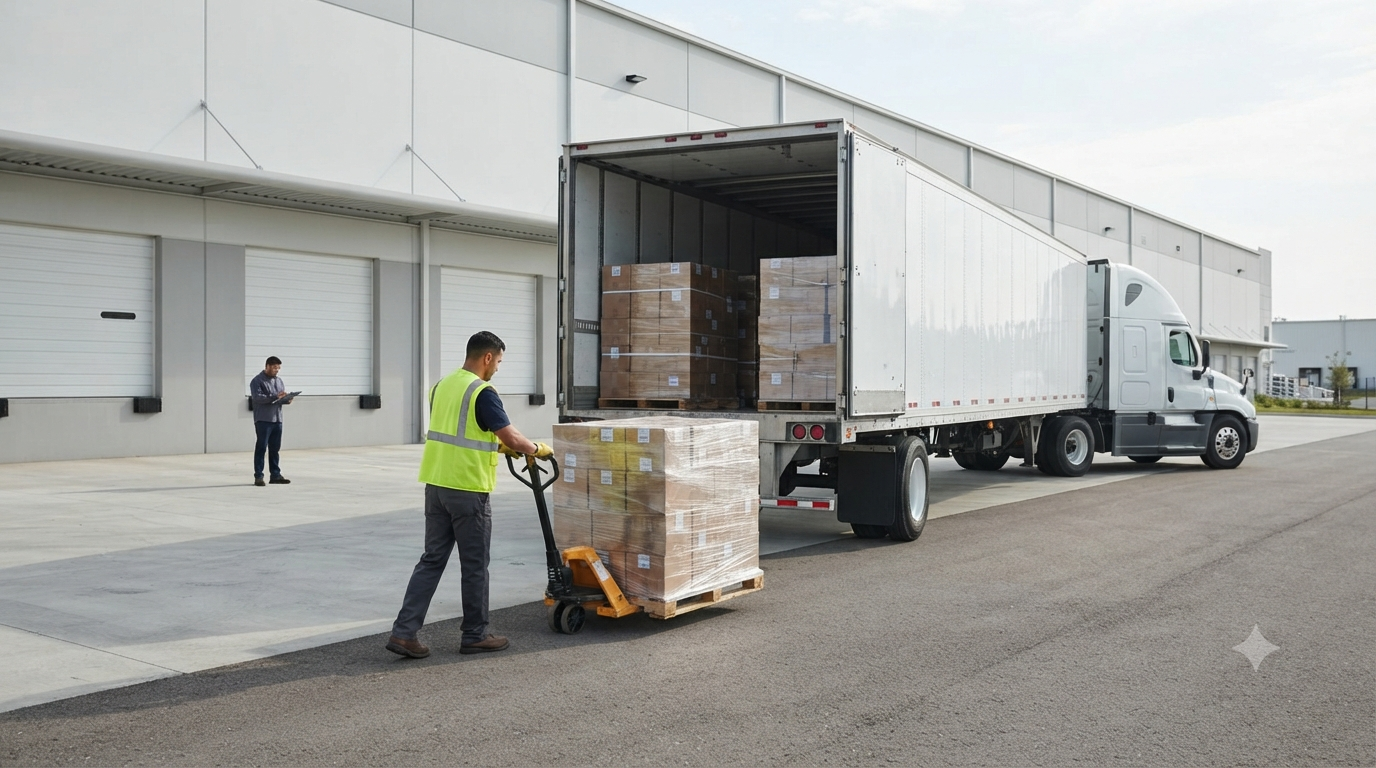
Cargo can vary widely
Hotshot carriers may haul machinery, vehicles, building materials or general freight. The cargo policy must be reviewed for commodity eligibility and value limits.
Own authority versus leased operation
The insurance structure changes based on whether the operator runs under their own motor carrier authority or leases to another carrier. Filings and primary liability obligations should be confirmed before quoting.
What can materially change the quote
Commercial trucking insurance is underwritten around the exposure. These are the details worth getting right before the submission goes to an insurer.
Truck and trailer GVWR/GCWR
CDL status and driver experience
Trailer type and stated value
Commodity mix and maximum cargo value
Local, regional or long-haul radius
Documents worth gathering early
A complete submission helps reduce back-and-forth and makes it easier to compare competing options on consistent information.
- Truck and trailer VINs
- Driver license/CDL information
- DOT/MC information
- Equipment values
- Sample broker requirements or rate confirmations
Common mistakes to check before binding
Premium matters, but the cheapest option can become expensive when a driver, commodity, vehicle or contract requirement does not fit the policy.
- Assuming a pickup-based operation can be insured like personal auto
- Understating maximum cargo value
- Ignoring trailer physical damage or interchange exposure
- Not checking weight thresholds and authority requirements
Do not compare truck insurance on premium alone
When two quotes look different, put the limits, deductibles, covered autos, drivers, cargo wording, endorsements and payment structure side by side. A lower number may reflect a higher deductible, narrower cargo appetite, different physical-damage valuation, excluded drivers or missing endorsements. The useful question is not simply “Which quote is cheaper?” but “Which quote covers the operation I intend to run?”
Bring the real operation—not a generic truck count.
ClearSpan can use your drivers, equipment, cargo, authority, contracts and current policy details to organize a more useful quote conversation.
A practical four-step quote process
Collect the risk
Drivers, units, cargo, radius, authority, loss runs and contract requirements.
Define the coverage
Match limits, deductibles, filings and endorsements to how the operation actually works.
Compare terms
Review insurer appetite and policy differences—not just the first premium number.
Keep it current
Update drivers, equipment and operating changes and prepare early for renewal.