Identify the business use
Describe whether the operation is household goods, final-mile delivery, general freight, moving, appliance delivery or another specialty. Contract requirements can differ substantially.
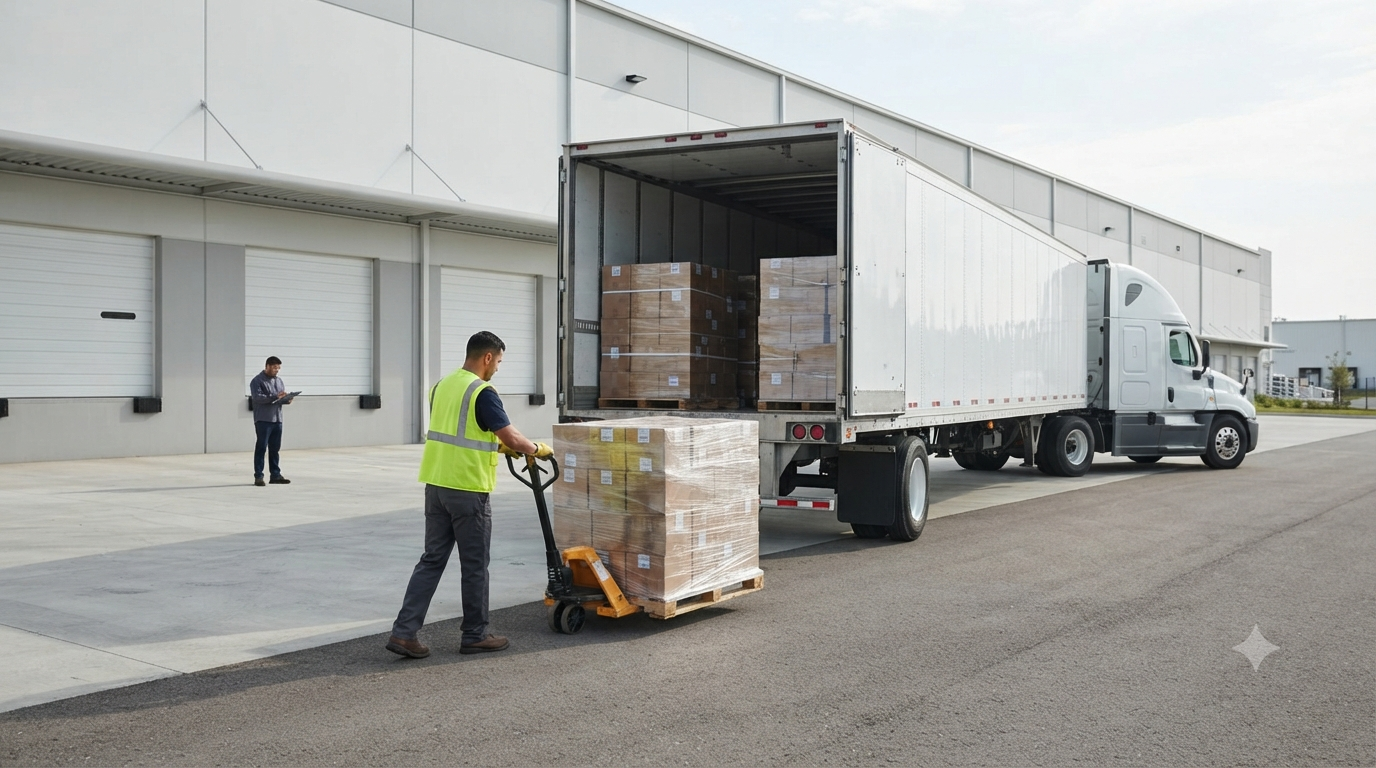
Cargo and loading exposures
Furniture, electronics, appliances and general freight can create different cargo limits and handling risks. Liftgates, pallet jacks and helper crews may also change the operational picture.
Commercial auto is only one piece
Depending on the business, cargo, general liability, workers compensation or other coverage may be relevant in addition to truck liability and physical damage.
What can materially change the quote
Commercial trucking insurance is underwritten around the exposure. These are the details worth getting right before the submission goes to an insurer.
GVWR and truck value
Local versus interstate radius
Employee versus contractor drivers
Cargo type, theft exposure and maximum values
Loading, unloading and premises activity
Documents worth gathering early
A complete submission helps reduce back-and-forth and makes it easier to compare competing options on consistent information.
- VINs and vehicle values
- Driver roster
- Customer contracts
- Cargo description and limits
- Current coverage/loss runs if renewing
Common mistakes to check before binding
Premium matters, but the cheapest option can become expensive when a driver, commodity, vehicle or contract requirement does not fit the policy.
- Insuring only the vehicle and overlooking cargo or general liability
- Failing to disclose residential delivery or installation activity
- Using drivers not shown or approved under the policy
- Assuming local radius automatically means low risk
Do not compare truck insurance on premium alone
When two quotes look different, put the limits, deductibles, covered autos, drivers, cargo wording, endorsements and payment structure side by side. A lower number may reflect a higher deductible, narrower cargo appetite, different physical-damage valuation, excluded drivers or missing endorsements. The useful question is not simply “Which quote is cheaper?” but “Which quote covers the operation I intend to run?”
Bring the real operation—not a generic truck count.
ClearSpan can use your drivers, equipment, cargo, authority, contracts and current policy details to organize a more useful quote conversation.
A practical four-step quote process
Collect the risk
Drivers, units, cargo, radius, authority, loss runs and contract requirements.
Define the coverage
Match limits, deductibles, filings and endorsements to how the operation actually works.
Compare terms
Review insurer appetite and policy differences—not just the first premium number.
Keep it current
Update drivers, equipment and operating changes and prepare early for renewal.